Why Insurers Are Handing Millions Back to Policyholders Just to Stop Churn
 By Chloe Bennett
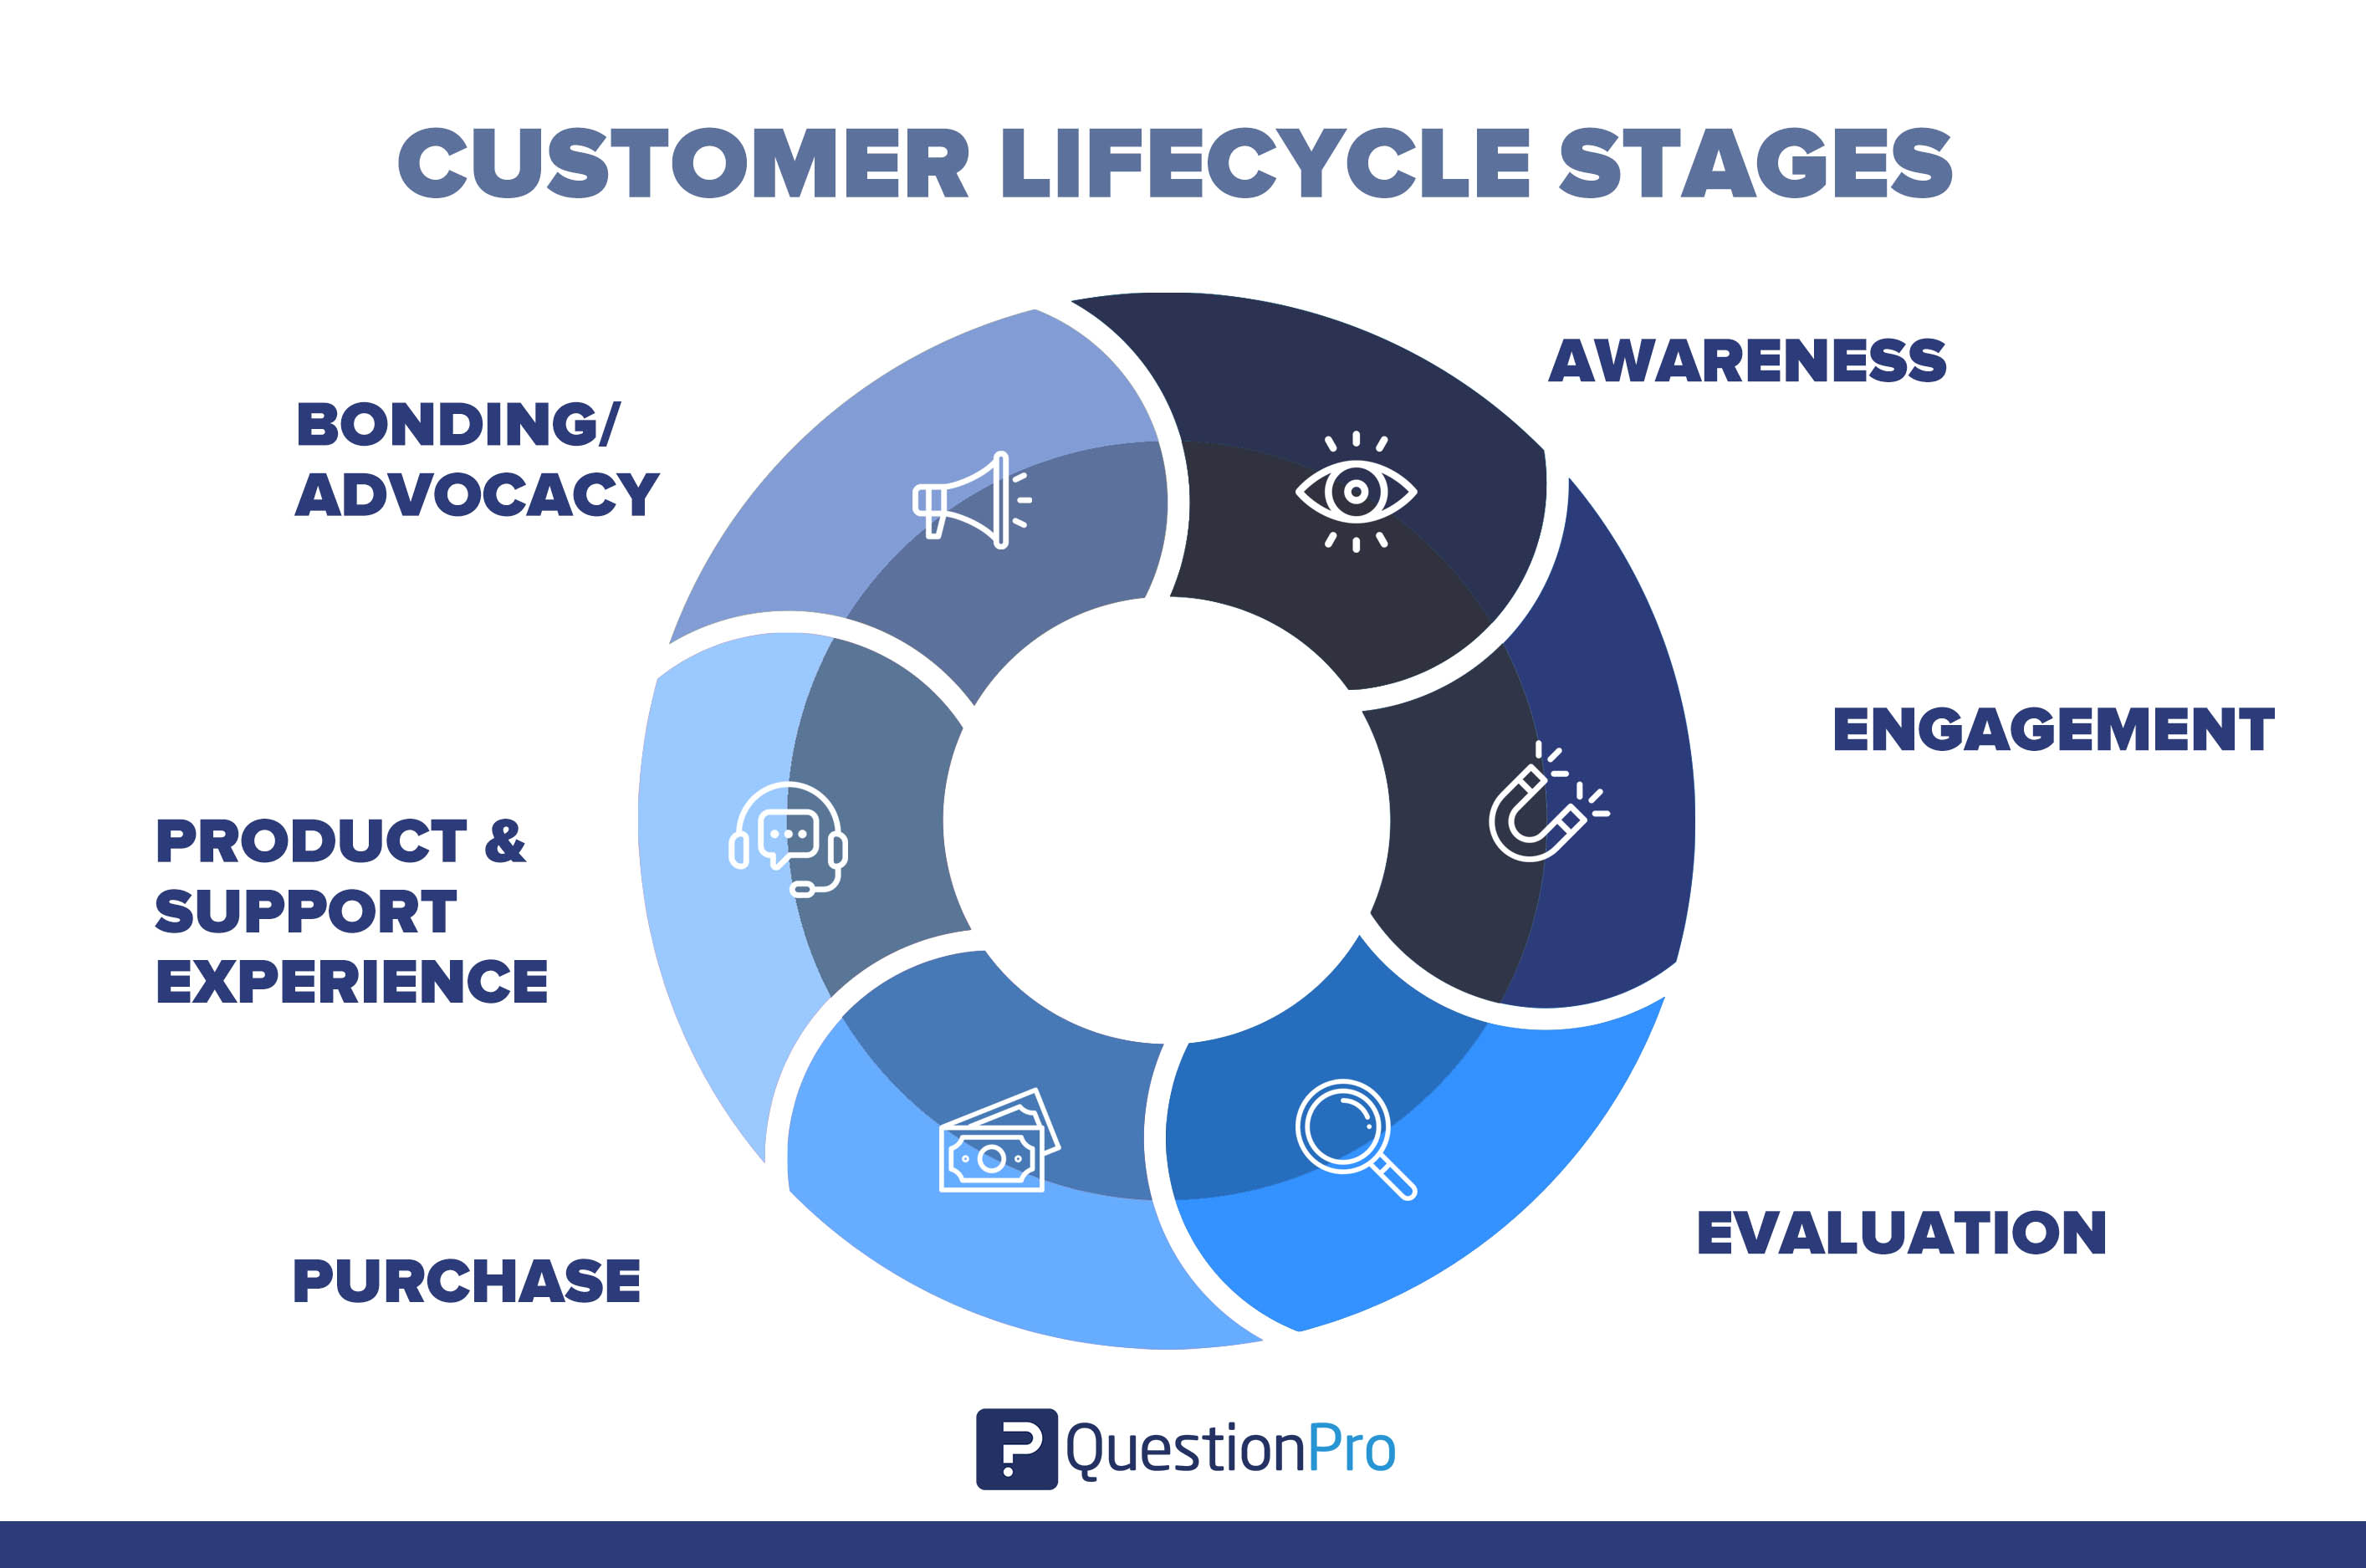
The shift toward aggressive retention spending is rooted in pure accounting. Acquiring personal auto accounts via national television ad campaigns, search engine keywords, and independent agent commissions has never been more expensive. Maintaining an existing policyholder at a lower margin yields far better combined ratios over a five-year horizon than continuously purchasing new business at inflated acquisition rates.
The table below contrasts the evolving economic parameters of personal auto lines over the past three operating cycles:
| Operating Metric | 2024 (Rate Shock Era) | 2025 (Peak Defection) | 2026 (Stabilization) |
|---|---|---|---|
| Average Policy Renewal Rate | 81.4% | 76.8% | 83.1% |
| Customer Acquisition Cost (CAC) | $520, $680 | $650, $920 | $580, $750 |
| Auto Insurance Shopping Activity | Elevated (Hot) | Historic Peak (Very Hot) | Moderating (Warm) |
| Retention Spend per At-Risk Account | $45, $80 | $110, $160 | $180, $260 |
| Average Telematics Participation Rate | 18% | 27% | 39% |
As demonstrated by these numbers, carriers are allocating substantially more capital directly to policy preservation. The return on investment remains clear: boosting customer retention by a mere 5% routinely improves aggregate underwriting profitability by 25% to 35% over the lifetime of a cohort.
Chloe Bennett explores the intersection of pop culture, streaming entertainment, digital trends, and contemporary lifestyle. Her weekly commentary reaches thousands of culture enthusiasts.
