Capital One Auto Loan Pre-Approval Exposed: What Dealers Hide About Your Rate
 By Alexander Ross
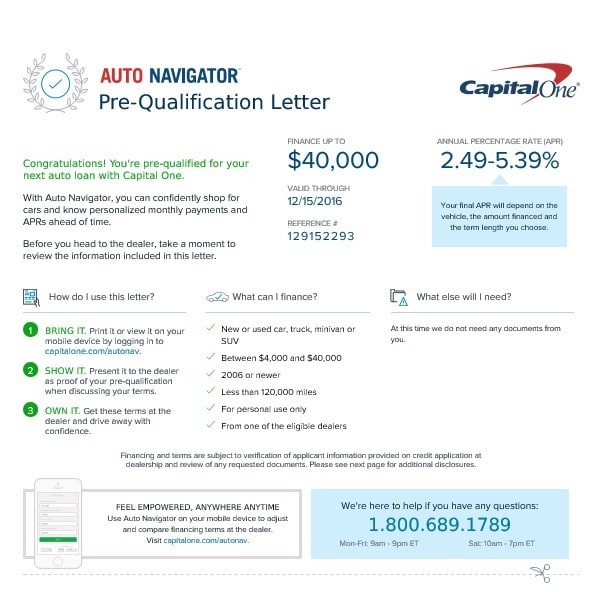
Capital One's program requires borrowers to purchase from its network of participating dealerships. You cannot bring an Auto Navigator approval to a private seller or an unapproved independent lot. This limitation concentrates power within franchised dealerships, where sales teams have refined ways to counter digital rate transparency.
When a customer arrives with a firm rate in hand, finance managers frequently turn to mandatory dealer add-ons to recover the profit margin they cannot capture through rate inflation.
Common tactics involve adding accessory charges directly to the itemized buyer's order:
- VIN etching packages billed at $495 (costing the dealer under $20).
- Pre-applied ceramic coatings or fabric guards running $895 to $1,495.
- Extended warranties and GAP policies presented as "mandatory requirements" to satisfy Capital One financing.
Capital One does not require extended service contracts or GAP coverage as a condition of loan approval. Claiming that a third-party warranty is mandatory to satisfy bank underwriting violates both federal lending laws and Capital One dealer policies. Any attempt by a salesperson to tie loan approval to an accessory or service contract signals an immediate compliance violation.
Alexander Ross has covered the video game industry for a decade, writing deep dives on game design, esports tournaments, VR developments, and gaming culture.
